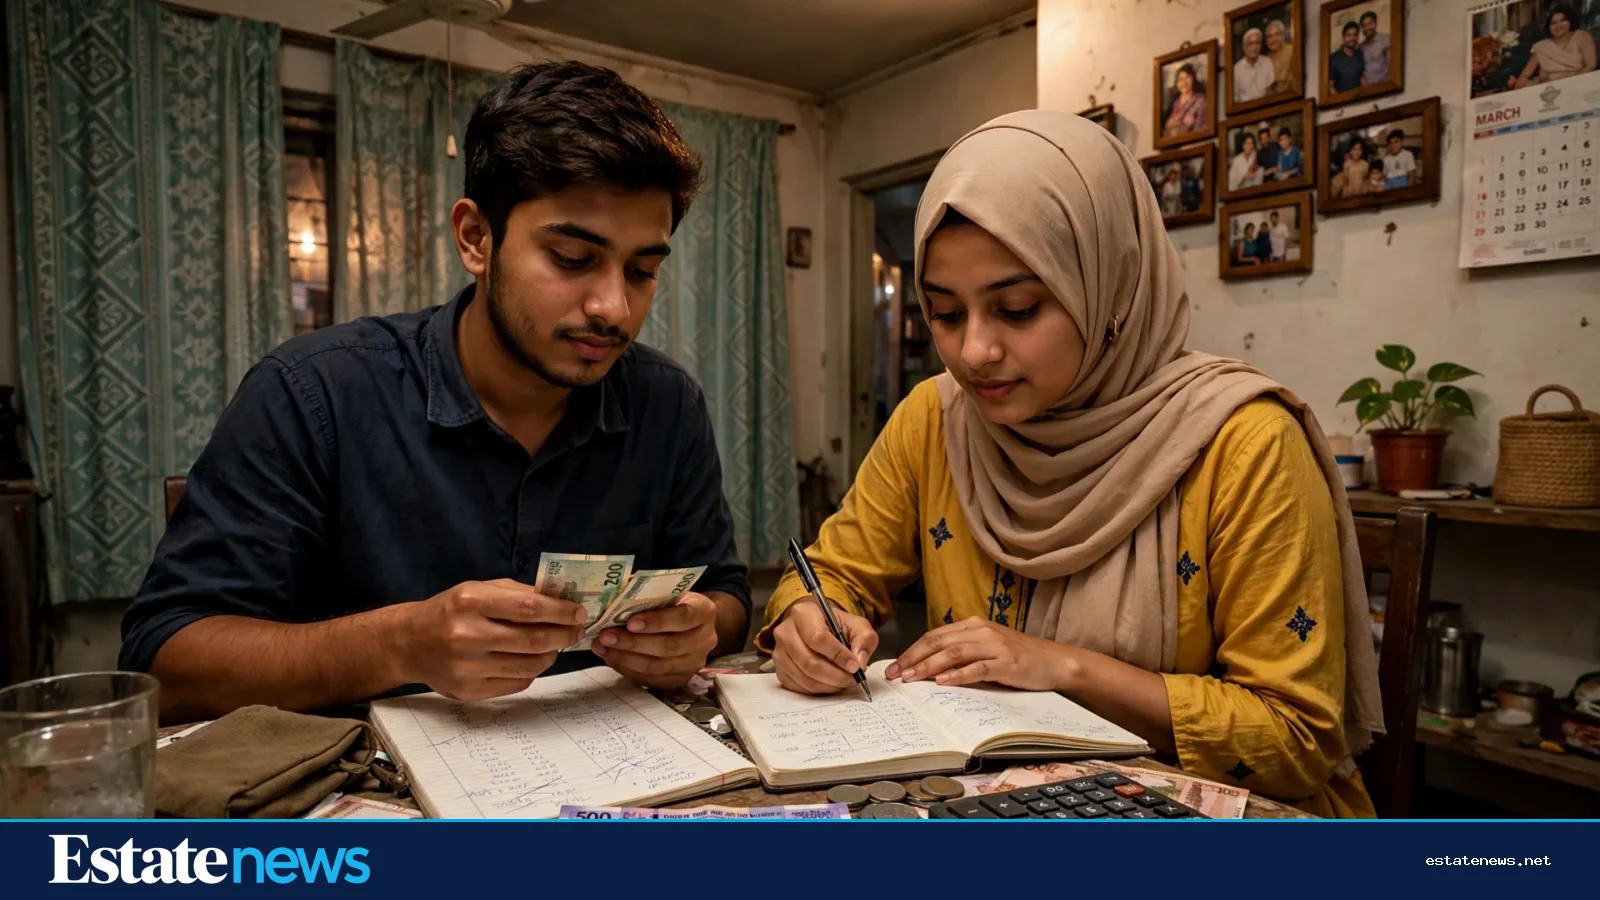
Start with the month, not the flat. A Dhaka household that rents, pays school fees and supports parents cannot save what is left at month end, because in most months nothing is left. The deposit plan that works is the one taken on payday, before the money spreads across bazar trips, ride fares and small loans to relatives.
Set the target from the loan, not from a dream flat. A bank will lend against income, the flat's papers and the household's other debts, and the deposit is the gap between the flat's price and that loan, plus registration, mutation and moving costs. Many buyers forget those extra costs and arrive at the bank with exactly the deposit and nothing for the rest. Keep a separate line for them from the start.
The monthly habit

A Deposit Pension Scheme, or DPS, fits salaried households because it takes a fixed amount every month. Prothom Alo reported that mobile-based DPS options through bKash start from Tk 500 a month, with weekly options from Tk 250, offered through banks including BRAC Bank, IDLC Finance, Dhaka Bank, Mutual Trust Bank and City Bank's Islamic service. Rates change with the bank and the term, and a one-year monthly DPS of Tk 1,000 was reported at 9 percent to 10 percent in that coverage. A separate comparison of savings options in late October 2026 put DPS rates at about 9 percent to 10 percent in general, with Midland Bank listing 10.25 percent for a three- or five-year women's DPS. Check the current rate sheet before opening anything, and read the early-closure terms. A DPS broken early usually pays far less profit, and that penalty is the price of the discipline it creates.
The arithmetic is plain, and it helps to see it written down. Saving Tk 15,000 a month for 36 months puts aside Tk 5,40,000 of principal, before any profit and before tax. Saving Tk 20,000 a month for the same period puts aside Tk 7,20,000. Saving Tk 10,000 a month puts aside Tk 3,60,000. None of these figures is a promise. Profit depends on the rate on the day, tax applies to interest, and a missed instalment can reduce the payout. Use the principal as the planning number, and treat profit as a cushion, not the plan.


Keep the emergency fund apart from the deposit. Three months of basic expenses in an ordinary savings account, reachable at once, should come before a long DPS. A job loss, a hospital bill or a family crisis in year two should not force a buyer to break the deposit scheme. If the household cannot fund both, the deposit target waits. That delay feels like failure, but it is the decision that keeps the plan alive.
Family help, in writing
Family help buys many first flats in Dhaka, and it causes many family arguments too. A gift is not a loan, and a loan is not a gift. Write down the amount, whether it must be repaid, over how long, and what happens if the flat is sold. If parents contribute from retirement savings, say so in the family, and ask whether that money is needed back. A bank may also ask where the deposit came from, so a paper trail helps there too: bank transfers, not cash handed over in an envelope with no record.
In year three, the plan changes shape. Get a bank's early view on loan eligibility before choosing a flat, and keep the deposit in a place that can be released on the bank's timetable. Visit flats with the total cost in mind, not just the asking price. A flat that needs Tk 3 lakh of work before anyone can live in it is not cheaper than a ready flat at a higher price. When the deposit is ready, the household that kept the monthly habit for three years has already proved the one thing a loan officer wants to know: that it can live on less than it earns, month after month.
This article is informational only and is not financial advice. Rates, tax rules and bank terms change, and a reader should confirm current terms with the bank before acting.