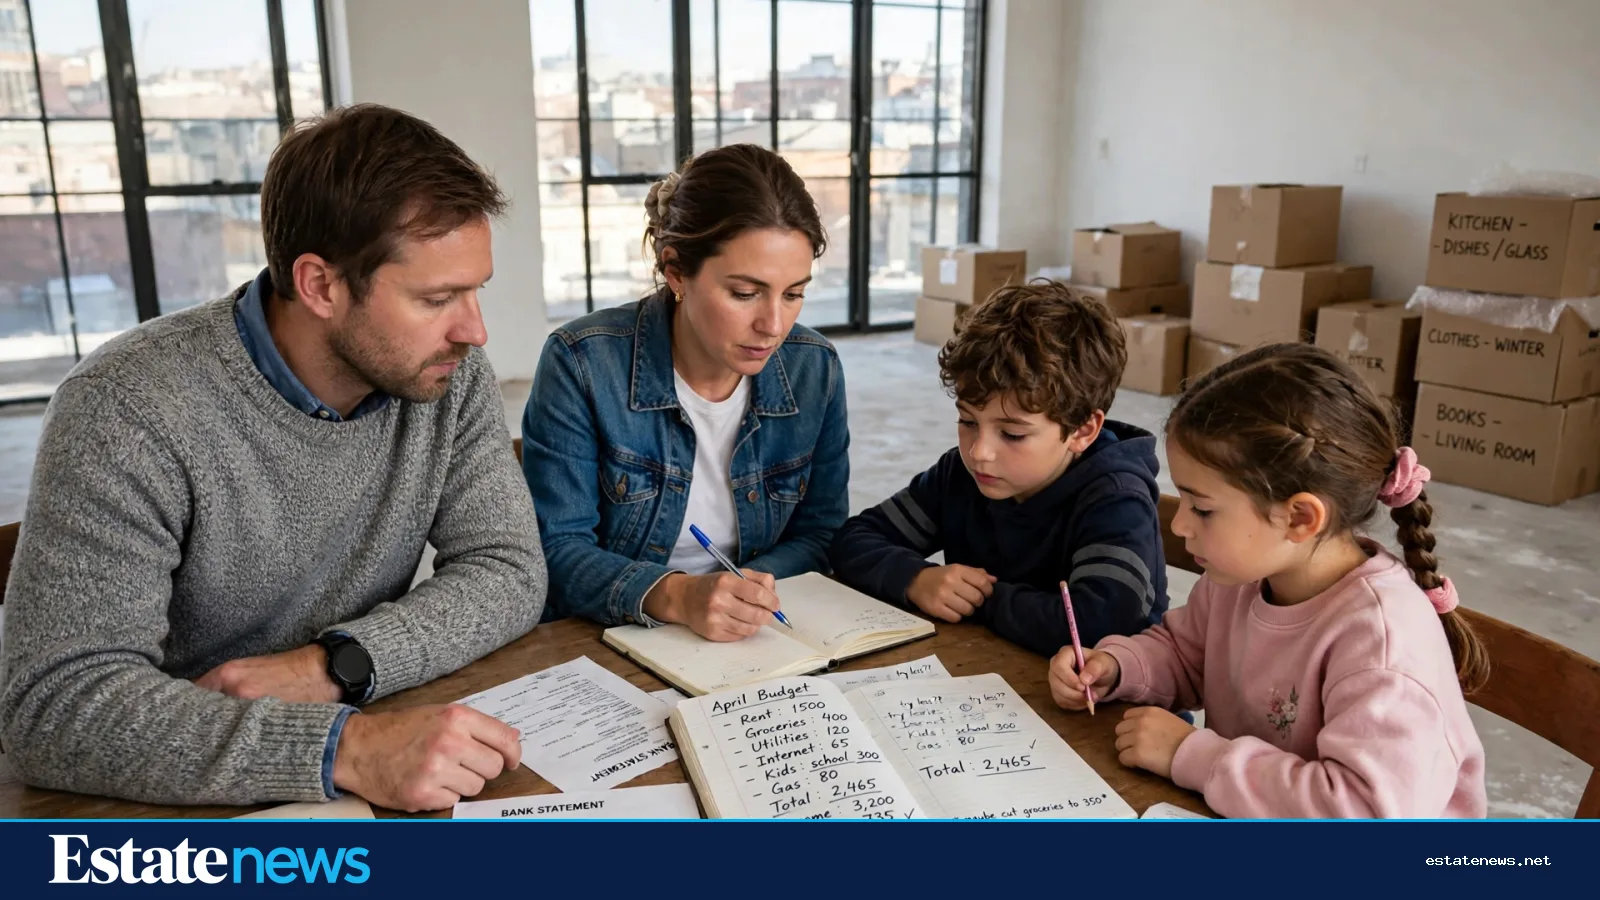
Every first-time buyer in Dhaka knows the flat's price before signing. Almost none knows the full cost of owning it before moving in. The difference is not a rounding error: buyer guides routinely estimate that the extras add 10 to 15 per cent on top of the purchase price, and the bills arrive in a rush, at exactly the moment the household's savings are at their lowest.
The costs fall into five groups. None of them is a secret. All of them are easy to miss when attention is fixed on the price per square foot.
1. The government charges

Registration is the largest single extra, and it is unavoidable. Stamp duty of 1.5 per cent of the deed value, a registration fee of about 1 per cent, local government tax of 2 to 3 per cent, source tax that varies with the location and class of land, and VAT of 2 per cent on new flats up to 1,600 square feet — 4.5 per cent above that — together come to roughly 8 to 14 per cent of the deed value, according to recent buyer guides. On a Tk 1 crore flat, that is Tk 8 to 14 lakh, payable in cash before the deed is registered. Buyers who budget only for the price discover this bill when it is too late to renegotiate.
2. The loan's own charges
A home loan is not just an interest rate. Lenders commonly charge a processing fee of around 0.3 to 1 per cent of the loan amount, and many loans carry insurance or documentation charges bundled into the facility. Some lenders also charge for valuation, legal verification and, later, for early settlement or for taking over the loan from another bank. The interest rate deserves the headlines — bank home-loan rates currently sit in a broad band of roughly 9 to 13 per cent, with the Bangladesh Bank policy rate at 9.5 per cent — but a loan that looks cheap on rate and expensive on fees can cost more overall. Ask for the full schedule of charges in writing, and compare loans on total cost, not on rate alone.
3. Service charges and the maintenance fund
A new building runs on money collected from its residents: lift maintenance, generator fuel, security staff, cleaning, common-area electricity and water pumping. Developers commonly collect a service-charge advance covering several months at handover, and some collect a one-time contribution to a building maintenance or sinking fund for major future repairs — lift replacement, roof work, repainting. These are legitimate costs, but they are rarely prominent in the sales conversation. Before signing, ask for the current monthly service charge per square foot, what it covers, and whether a separate fund contribution is due at handover.
4. Utility connections and deposits
Electricity, gas, water and sewerage connections are sometimes included in the price and sometimes not, and the distinction is worth a written answer. Where they are not included, buyers report connection and deposit costs that can run into tens of thousands of taka per utility, varying by location and by whether the building's infrastructure is already in place. Gas connections in particular have become slower and less certain in parts of Dhaka, so a flat promised with a gas line and a flat delivered with one are not always the same thing. Confirm each utility in writing, and budget for deposits and meter charges.
5. Furnishing, finishing and the first year
A bare flat is not a home. Lights, fans, kitchen fittings, window grilles, curtains, wardrobes and basic furniture are needed before the first night, and finishing work — painting touch-ups, additional electrical points, bathroom fittings — is frequently more extensive than the handover inspection suggested. Beyond furnishing, the first year of ownership brings its own bills: minor defects that appear after moving in, appliance purchases, and the service charge itself, which is a permanent monthly cost that renters in some buildings partly avoid. A realistic furnishing and first-year budget for a mid-sized flat is several lakh taka, not a token amount.
How to protect yourself
- Get a written, itemised list from the developer of every charge included in the price and every charge excluded from it.
- Budget registration charges at 10 to 12 per cent of the deed value as a planning figure, and confirm the exact amount at the sub-registry office before the registration date.
- Ask the lender for every fee attached to the loan, not just the rate.
- Ask the building's residents' association, where one exists, what the real monthly service charge is — the developer's figure and the residents' figure sometimes differ.
- Keep a contingency of at least 5 per cent of the flat's price beyond your furnishing budget for first-year surprises.
A flat is a long-term commitment, and its true cost is the price plus everything it takes to live in it. Buyers who count only the price are not getting a bargain. They are getting a surprise.
This article is for information only and is not financial advice. Charges and tax rules change; verify current rates with your bank, lawyer and the relevant utility offices before purchase.
Follow Estate News on Facebook for daily property, market and money updates: https://www.facebook.com/profile.php?id=61593817347872